Boca Villas Home Values: Why Price per Square Foot Splits
August 20, 2026
August 20, 2026
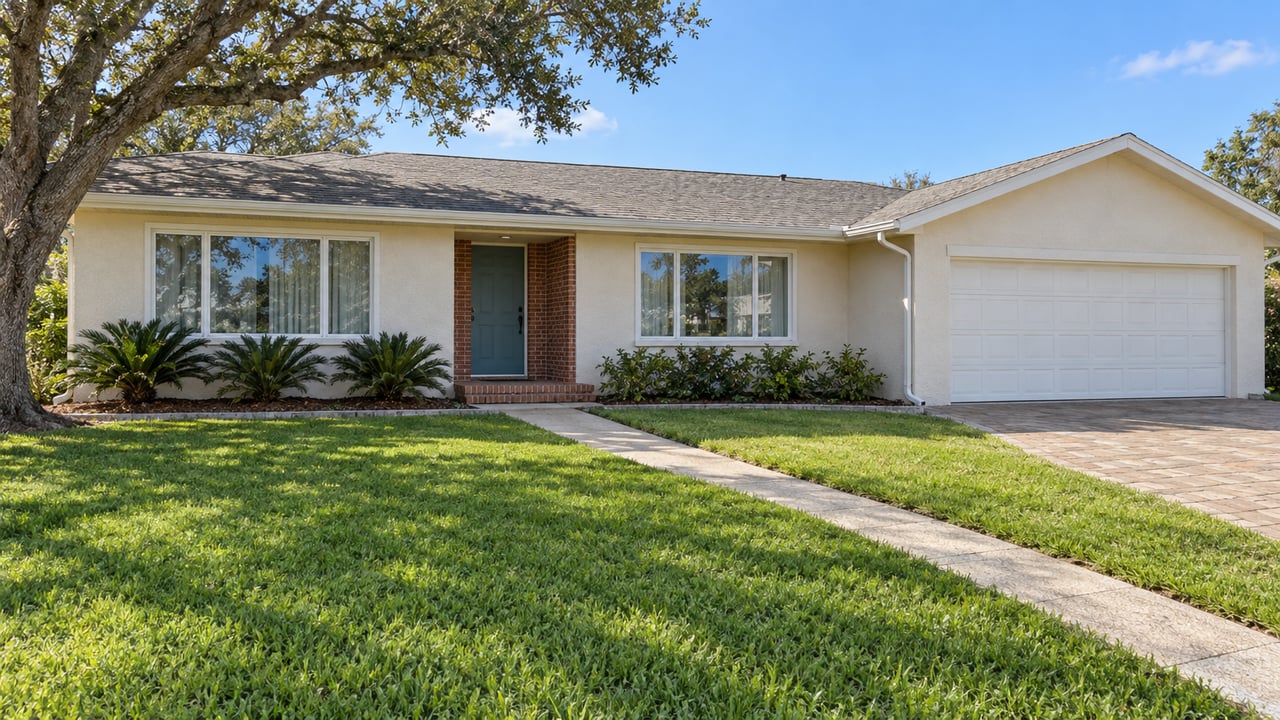
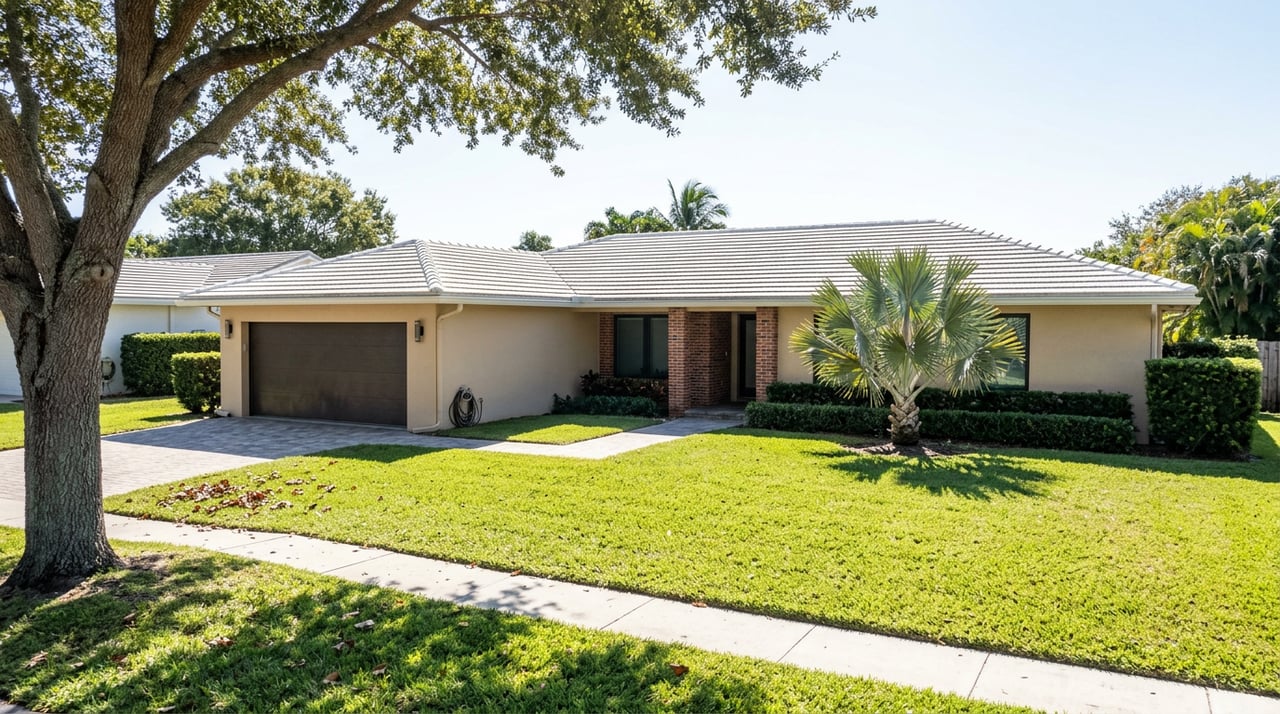
Say you own a 1968 ranch in Boca Villas. You put in a new kitchen five years ago, refinished the terrazzo, added impact windows on the street-facing rooms. The roof was replaced by a previous owner and is now nineteen years old. You assume that when you list, you'll land somewhere in the middle of the market, ahead of the fixer-uppers and behind the new-construction estates two blocks over. Then your agent pulls comps, and there is no middle. The recent closings are either land-value teardowns priced in the low seven figures or brand-new five- and six-bedroom estates clearing $700 or $900 a square foot. Nothing in between has traded in months.
That gap is not a fluke of timing. It is the shape of the Boca Villas market right now, and it has less to do with buyer taste than with what an insurance company will and will not write a policy on.
Look at the ten most recent closed sales in Boca Villas, running from February through June 2026. Every single one is new construction or a full rebuild, five or more bedrooms, between roughly 4,400 and 9,300 total square feet. Price per square foot across those ten sales ranged from about $495 to $960, averaging close to $765. That is a wide spread for homes that are, on paper, the same product category: brand-new, code-compliant, fully insurable construction.
| Closed | Price | Total Sq Ft | Approx. $/Sq Ft |
|---|---|---|---|
| June 2026 | $6.75M | 9,344 | $722 |
| June 2026 | $3.725M | 6,272 | $595 |
| June 2026 | $6.05M | 6,309 | $959 |
| June 2026 | $3.695M | 4,416 | $837 |
| May 2026 | $4.3M | 6,784 | $634 |
| May 2026 | $5.45M | 6,935 | $786 |
| May 2026 | $4.9M | 6,568 | $746 |
| April 2026 | $5.8M | 6,358 | $912 |
| April 2026 | $4.2M | 4,378 | $960 |
| February 2026 | $3.2M | 6,466 | $495 |
What is missing from that list is the ranch. Boca Villas was built out with several hundred single-family homes in the 1950s and 1960s, and agents active in the neighborhood consistently describe the entry point for an original, land-value teardown as starting around one million dollars, with new construction running past five million once the lot is rebuilt. What almost never shows up in a closed-sale list is the home in between: updated enough to live in comfortably, not new enough to satisfy an underwriter. That absence is the barbell. The middle is not just underperforming on price. It is barely transacting at all.
The mechanism behind this is Florida's roof-age insurance rule, and it is worth understanding in detail because it shapes financing, not just premiums.
Under Florida Statute 627.7011, an insurer cannot refuse to write or renew a homeowners policy solely because a roof is under 15 years old. Past that mark, the protection flips: the insurer can require an inspection, and if a licensed inspector does not certify at least five years of remaining useful life, coverage can be declined or shifted from Replacement Cost Value to Actual Cash Value. On a 17-year-old shingle roof, that shift alone can mean a claim payout closer to a third of what a full replacement would cost. Tile and metal roofs generally hold up longer than shingle, but many carriers apply the same age-based scrutiny regardless of material once a roof clears the 15 to 20 year mark.
This matters well beyond the premium. A lender qualifying a buyer folds the insurance premium into the monthly PITI payment. If a carrier won't write full replacement coverage, or if the premium jumps because the home lands with Citizens Property Insurance as a fallback, the buyer's debt-to-income math tightens and the loan amount they qualify for shrinks. A home with an unresolved roof-age question is not just harder to insure. It is harder to finance, which shrinks the buyer pool down to cash offers willing to absorb the risk.
That is precisely the trap the renovated middle falls into. A 1968 ranch with a new kitchen and a 19-year-old roof looks move-in ready in photos, but it sits in exactly the zone where insurers start asking for documentation and lenders start hesitating. A teardown candidate escapes the problem because the buyer is pricing the lot, not the structure, and has no intention of insuring the existing roof past closing. New construction escapes it because the roof was installed to current code last year and comes with full Replacement Cost coverage from day one. The updated ranch in between gets penalized for being just old enough to raise a question and not new enough to answer it.
If your home falls into that gap, price and marketing strategy diverge from what a typical listing consultation covers.
If you are shopping the middle of Boca Villas rather than a new build, ask about roof age before you fall in love with a kitchen. Florida's average homeowners premium in 2026 runs roughly $3,240 to $4,500 a year statewide, with coastal South Florida properties frequently landing between $5,830 and $7,290. That range shifts hard based on roof age and certification status, so get an insurance quote before you write an offer, not after your lender's underwriter flags the file. If the seller already has a roof certification and wind mitigation report in hand, that is worth more in practice than another year of granite countertops.
There is some room for optimism on the insurance side. Citizens Property Insurance voted to file for an average 2.6 percent rate cut for personal lines starting in June 2026, part of a broader softening after tort reform reduced litigation costs for carriers statewide. That does not undo the age-based scrutiny built into the statute, but it does mean the fallback option, if a private carrier declines, is a little less punishing than it has been in recent years.
None of this changes why people want Boca Villas in the first place. It sits behind Mizner Park, close enough to walk to dinner at Max's Grill or drinks at Loch Bar and Tanzy, with the Boca Raton Museum of Art and Royal Palm Place a short stroll further. Some listings in the neighborhood's eastern pocket market themselves under the name the Golden Triangle, the same high-demand corner of East Boca where land has been scarce for decades. That location is exactly why teardown economics work here in a way they wouldn't in a less walkable part of the city, and why the barbell shows up so clearly in the data. Buyers are willing to pay land-value prices for the lot or full-freight prices for a finished new build. What they are not lining up for, at least not yet, is the home stuck in between.
Citywide, the first quarter of 2026 showed Boca Raton's inventory expanding and cumulative days on market stretching to around 99 days on average, a double-digit increase over the same period in 2025. Turnkey luxury product in prime East Boca locations like Boca Villas continued to close quickly during that same quarter even as standard listings took longer to find the right buyer. That split is the same barbell playing out at the scale of the whole city, and it is one more reason a mid-vintage, partially updated home benefits from a pricing strategy built around its actual insurance and financing profile, not just its finishes.
If you're weighing whether your Boca Villas home is a teardown, a certification candidate, or ready to compete with new construction, that is exactly the kind of call The Bahn Group makes for a living. Get a Free Home Valuation and we'll walk the numbers with you before you list.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
Stay up to date on the latest real estate trends.
Brian has a reputation for consistently carrying one of the most impressive luxury listing platforms in the marketplace. Contact Brian today for a free consultation for buying, selling, renting or investing in Boca Raton, Florida.